The information provided is of general nature only and does not take into account your personal objectives, financial situations or needs. Before acting on any information provided, you should consider whether the information is suitable for you and your personal circumstances and if necessary, seek appropriate professional advice. All opinions, conclusions, forecasts or recommendations are reasonably held at the time of compilation but are subject to change without notice. Past performance is not an indication of future performance. Go Markets Pty Ltd, ABN 85 081 864 039, AFSL 254963 is a CFD issuer, and trading carries significant risks and is not suitable for everyone. You do not own or have any interest in the rights to the underlying assets. You should consider the appropriateness by reviewing our TMD, FSG, PDS and other CFD legal documents to ensure you understand the risks before you invest in CFDs. These documents are available here.
Any references to Australian or international shares, sectors, indices, ETFs, crypto-related stocks or other instruments are provided for market commentary and watchlist purposes only and do not constitute a recommendation, offer or solicitation to buy, sell or hold any financial product or adopt any investment strategy. International markets may involve additional risks, including currency fluctuations, regulatory differences, market structure differences, reduced liquidity and higher volatility. Company-specific, sector-specific and macroeconomic risks may also affect performance.
Commentary on geopolitical developments, economic data, central bank decisions, earnings, policy changes and other global or financial market events is based on information available at the time of publication and may change without notice. Such events can lead to sudden market moves, price gaps, reduced liquidity, wider spreads and increased volatility, particularly in leveraged products such as CFDs. Forward-looking statements, expectations and scenario analysis are inherently uncertain and should not be relied on as guarantees of future market behaviour or outcomes.
Japanese Yen remains subdued as higher oil increases import costs
- Japanese Yen struggles as high crude oil prices weigh on Japan's energy-importing economy amid Israeli election uncertainty.
- Bank of Japan expects to hold interest rates steady this Friday, with markets pricing in a December hike.
- Federal Reserve is projected to maintain its target rate at 3.75%-4.0% today, while investors await signals for December.
USD/JPY continues its winning streak for the fourth consecutive day, trading around 158.00 during Asian hours on Wednesday. The pair appreciates as the Japanese Yen (JPY) faces challenges amid rising crude oil prices, which place renewed cost pressures on major energy-importing economies.
Oil prices rose as global financial markets tracked ongoing election results in Israel that could shift the course of the Middle East conflict. Exit polls suggest a tightly contested election, showing Prime Minister Benjamin Netanyahu tied with opposition leader Gadi Eisenkot, leaving neither bloc with a clear majority as counting continues. Despite the deadlock, the preliminary results point to diminishing support for Netanyahu, who has been a dominant force in Israeli politics while leading the country through nearly three years of conflict.
The Bank of Japan (BoJ) is widely expected to hold interest rates steady at its upcoming Friday policy meeting. This follows a cumulative 50 basis points of rate hikes delivered earlier in the year, as policymakers pause to assess the impact of previous tightening. However, market participants continue to anticipate another rate increase before the end of the year, with pricing strongly favoring a December hike.
Similarly, the Federal Reserve (Fed) is projected to keep its benchmark interest rate unchanged within the target range of 3.75% to 4.0% at Wednesday's decision. According to the CME FedWatch Tool, markets are pricing in a 92.8% probability of a rate hold for the October meeting. Investors will closely analyze remarks from Fed Chair Kevin Warsh for signals regarding the future policy trajectory, particularly as markets assign an 84.4% chance to a rate hike in December.
Technical Analysis:
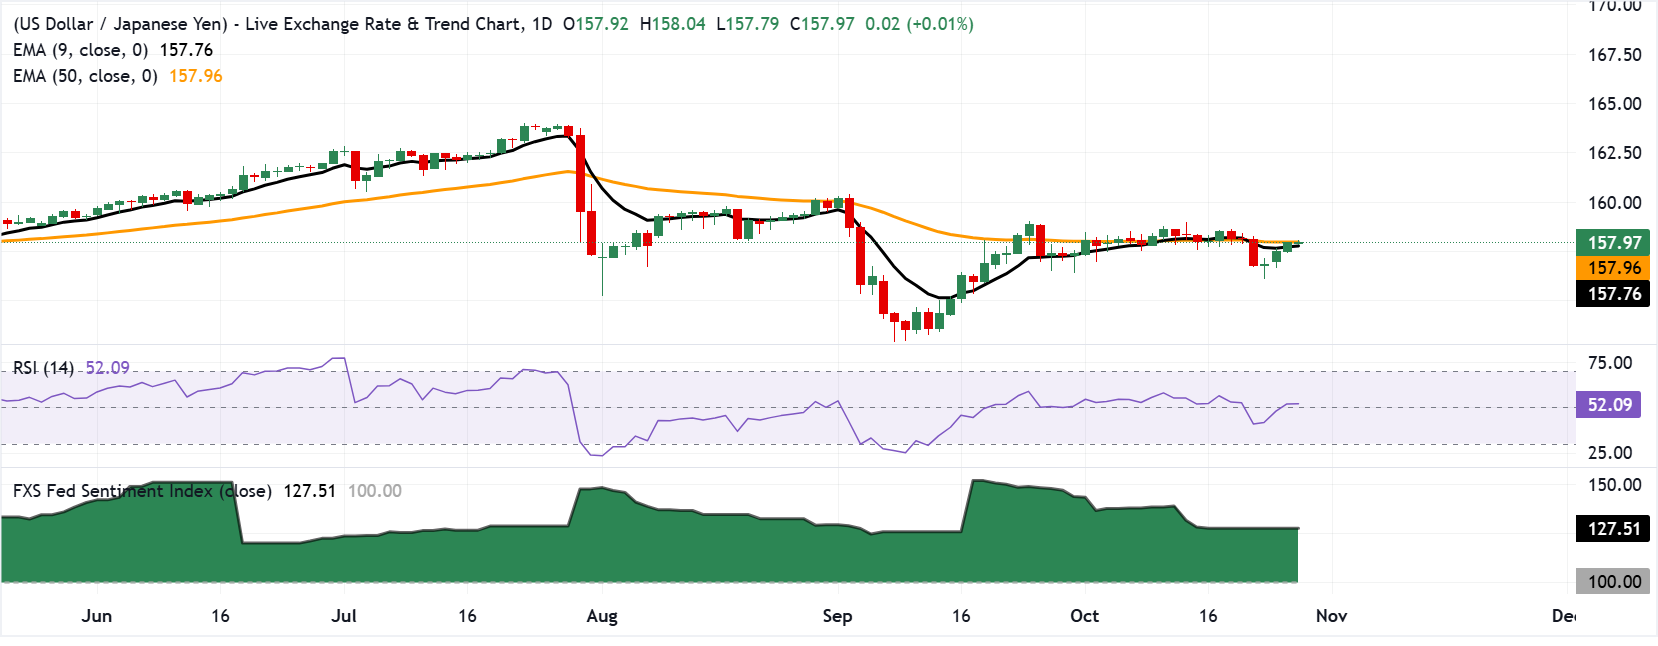
In the daily chart, USD/JPY trades at 158.00, holding a constructive bullish bias as spot remains above both the short-term and medium-term Exponential Moving Averages (EMAs). The 50-period EMA at 157.96 and the nine-period EMA at 157.76 sit just below price, suggesting underlying dip-buying interest, while the 14-day Relative Strength Index (RSI) around 52 keeps momentum in neutral-to-positive territory rather than in overbought conditions.
On the downside, immediate support emerges at the 50-period EMA near 157.96, with the nine-period EMA at 157.76 reinforcing a nearby demand zone on any pullback. A deeper slide would find more remote structural backing in the broader FXS Fed Sentiment Index base around 127.51, although that lies far from current spot levels and serves mainly as a longer-term macro reference.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Japanese Yen FAQs
The Japanese Yen (JPY) is one of the world’s most traded currencies. Its value is broadly determined by the performance of the Japanese economy, but more specifically by the Bank of Japan’s policy, the differential between Japanese and US bond yields, or risk sentiment among traders, among other factors.
One of the Bank of Japan’s mandates is currency control, so its moves are key for the Yen. The BoJ has directly intervened in currency markets sometimes, generally to lower the value of the Yen, although it refrains from doing it often due to political concerns of its main trading partners. The BoJ ultra-loose monetary policy between 2013 and 2024 caused the Yen to depreciate against its main currency peers due to an increasing policy divergence between the Bank of Japan and other main central banks. More recently, the gradually unwinding of this ultra-loose policy has given some support to the Yen.
Over the last decade, the BoJ’s stance of sticking to ultra-loose monetary policy has led to a widening policy divergence with other central banks, particularly with the US Federal Reserve. This supported a widening of the differential between the 10-year US and Japanese bonds, which favored the US Dollar against the Japanese Yen. The BoJ decision in 2024 to gradually abandon the ultra-loose policy, coupled with interest-rate cuts in other major central banks, is narrowing this differential.
The Japanese Yen is often seen as a safe-haven investment. This means that in times of market stress, investors are more likely to put their money in the Japanese currency due to its supposed reliability and stability. Turbulent times are likely to strengthen the Yen’s value against other currencies seen as more risky to invest in.
Related Articles