The information provided is of general nature only and does not take into account your personal objectives, financial situations or needs. Before acting on any information provided, you should consider whether the information is suitable for you and your personal circumstances and if necessary, seek appropriate professional advice. All opinions, conclusions, forecasts or recommendations are reasonably held at the time of compilation but are subject to change without notice. Past performance is not an indication of future performance. Go Markets Pty Ltd, ABN 85 081 864 039, AFSL 254963 is a CFD issuer, and trading carries significant risks and is not suitable for everyone. You do not own or have any interest in the rights to the underlying assets. You should consider the appropriateness by reviewing our TMD, FSG, PDS and other CFD legal documents to ensure you understand the risks before you invest in CFDs. These documents are available here.
Any references to Australian or international shares, sectors, indices, ETFs, crypto-related stocks or other instruments are provided for market commentary and watchlist purposes only and do not constitute a recommendation, offer or solicitation to buy, sell or hold any financial product or adopt any investment strategy. International markets may involve additional risks, including currency fluctuations, regulatory differences, market structure differences, reduced liquidity and higher volatility. Company-specific, sector-specific and macroeconomic risks may also affect performance.
Commentary on geopolitical developments, economic data, central bank decisions, earnings, policy changes and other global or financial market events is based on information available at the time of publication and may change without notice. Such events can lead to sudden market moves, price gaps, reduced liquidity, wider spreads and increased volatility, particularly in leveraged products such as CFDs. Forward-looking statements, expectations and scenario analysis are inherently uncertain and should not be relied on as guarantees of future market behaviour or outcomes.
欧元区GDP将成为欧元从新低反弹后的下一个焦点
- 欧元/美元在跌破10月14日低点后反弹至1.1200下方。
- 欧洲央行行长拉加德表示,在一致决定按兵不动后,12月加息可能性较大。
- 10月欧元区通胀数据将于11月4日周三公布,此前为3.8%。
欧洲央行(ECB)行长拉加德表示,12月再次加息仍有可能,欧元/美元已从10月14日低点下方攀升至周三高点上方。该货币对一度跌至1.1100上方后反转,目前交投于1.1200下方,接近时段高点,并有望连续第二个交易日上涨。
在伊朗战争推高能源价格后,欧洲央行已连续两次加息,将存款利率维持在2.50%。欧洲央行行长拉加德表示,在一致决定维持利率不变之前,曾讨论过第三次加息,而欧元/美元在她回答提问时开始攀升。货币市场认为12月加息的概率已升至80%以上。
欧洲央行行长拉加德在决议公布前发布的一段视频中表示,她将于2月7日离任,较其任期结束提前约9个月。欧元/美元的时段低点出现在随后公布的利率决议时, 高盛表示,无论谁接替她,欧洲央行的表现都可能大致相同。
日程安排
欧元区第三季度增长初值将于GMT时间周五10:00公布,预期为0.2%,前值为0.6%;欧洲央行首席经济学家连恩将于GMT时间16:10发表讲话。10月欧元区通胀数据将于11月4日GMT时间10:00公布,9月为3.8%。这三项数据都将影响12月加息预期。
美国第三季度就业成本指数将于GMT时间周五12:30公布,预期为0.8%,前值为0.9%。美国供应管理协会(ISM)服务业指数将于11月4日GMT时间15:00公布,前值为54.9,恰逢美国中期选举后的第二天。这两项数据都将影响美联储12月的下一步行动。
图表方面
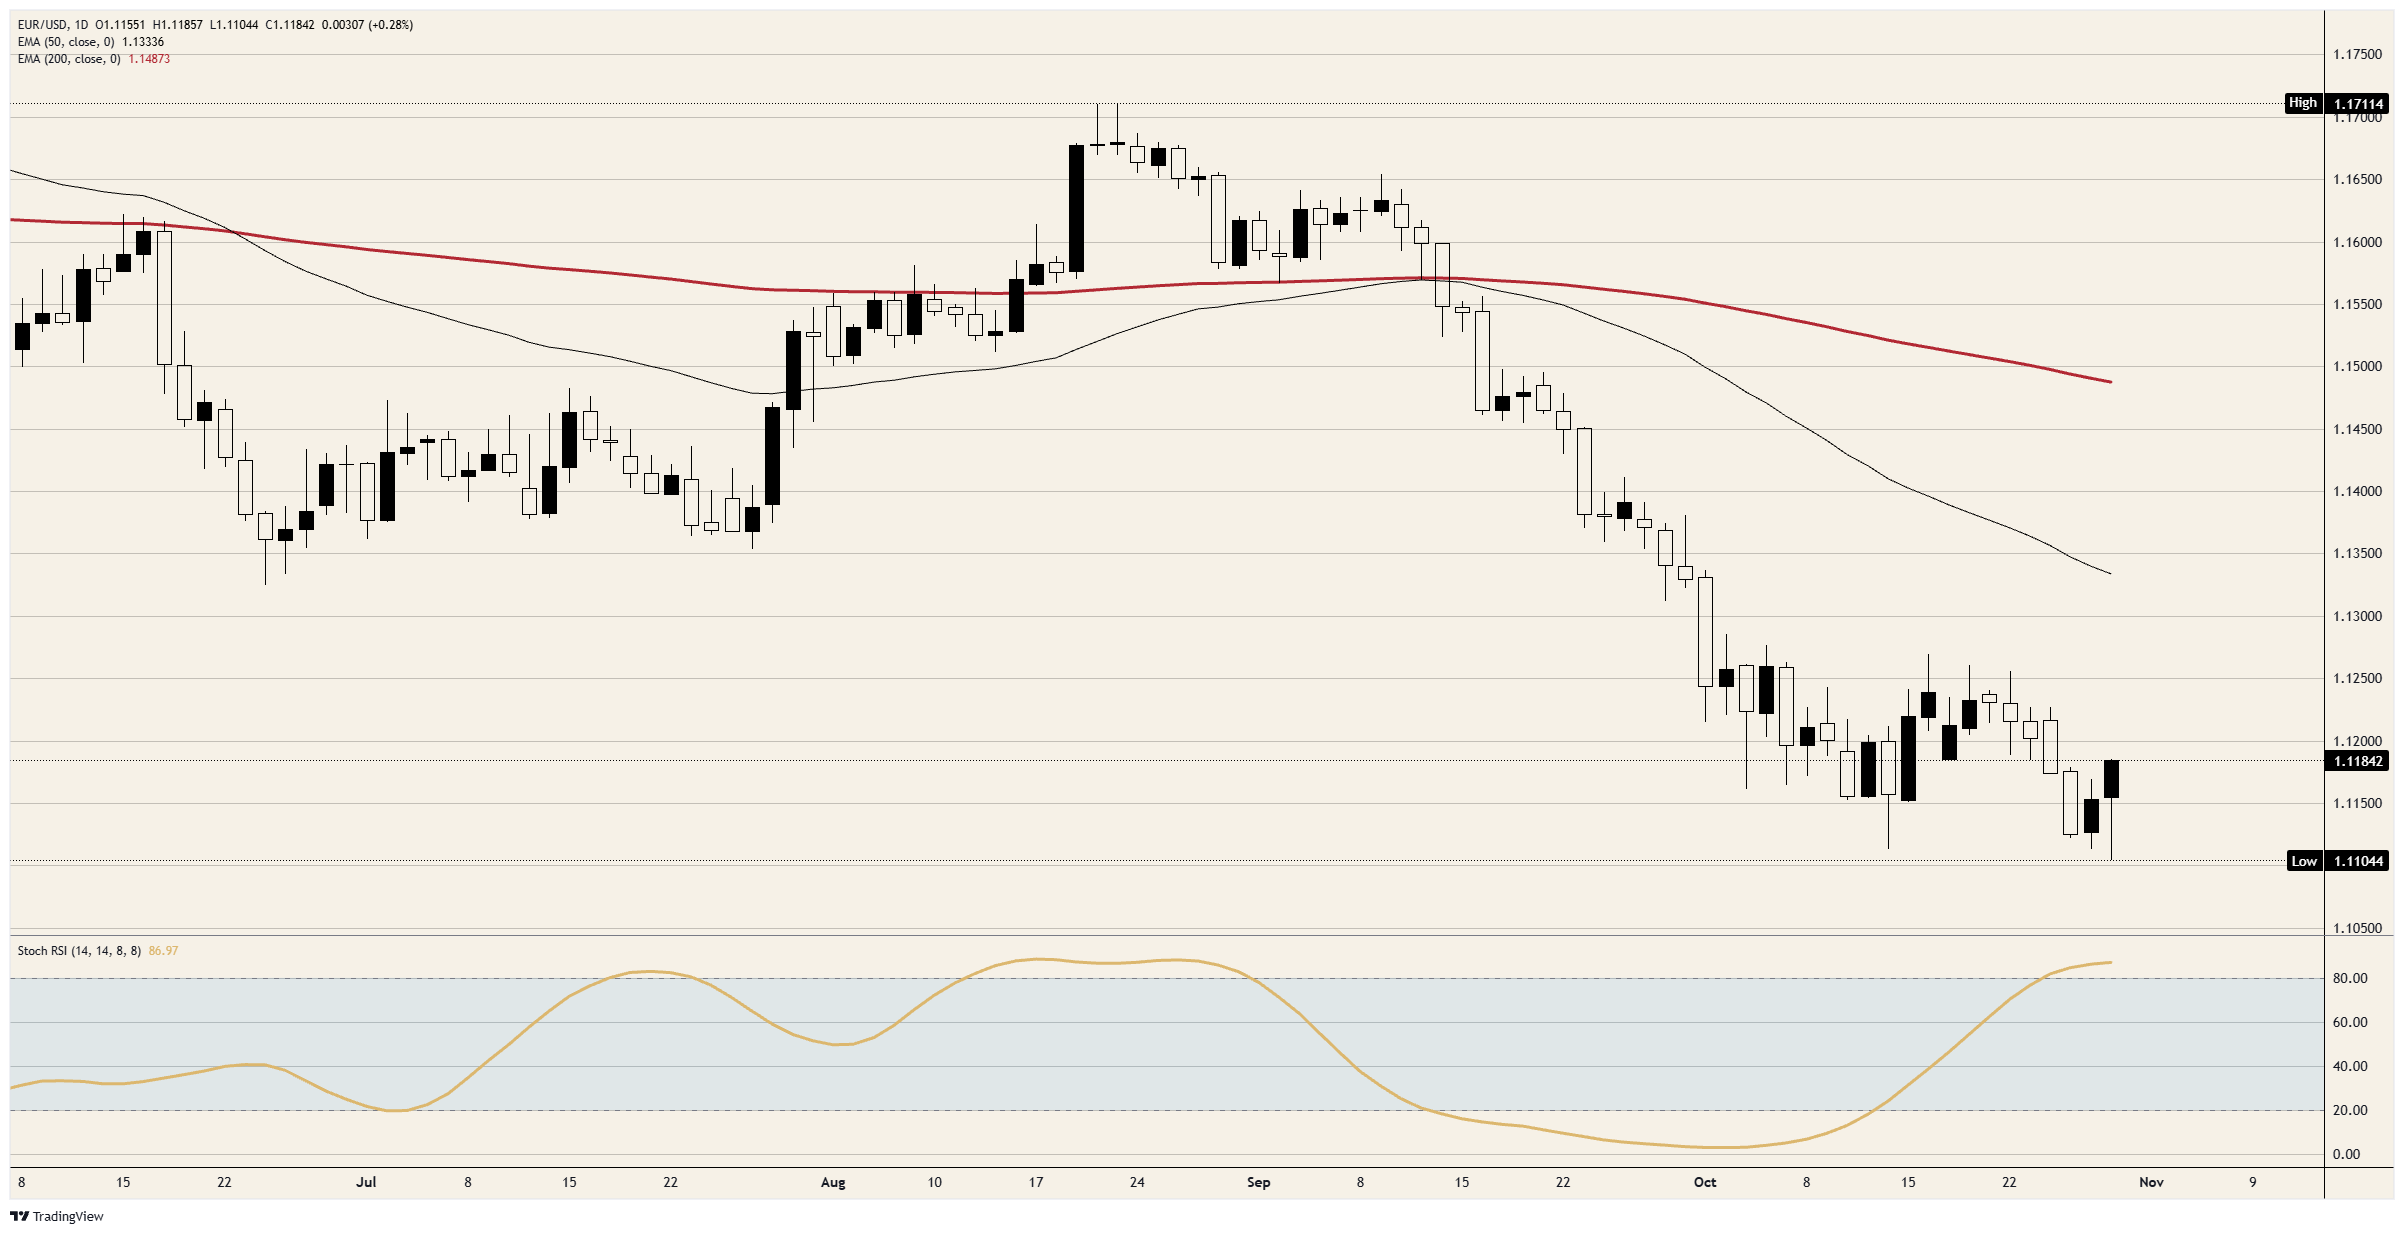
从时段低点反弹后,欧元/美元已收复自8月高点以来跌幅的大约八分之一。欧元/美元仍比其50日指数移动平均线(EMA)低约150点。50日均线在9月中旬下穿200日均线,两者相距约1.5美分。
欧元/美元日线图
欧元常见问题(FAQ)
欧元是属于欧元区的19个欧盟国家的货币。它是仅次于美元的世界上交易量第二大的货币。2022年,欧元占外汇交易总量的31%,日均交易额超过2.2万亿美元。欧元/美元是世界上交易量最大的货币对,约占所有交易的30%,其次是欧元/日元(4%),欧元/英镑(3%)和欧元/澳元(2%)。
位于德国法兰克福的欧洲中央银行是欧元区的储备银行。欧洲央行设定利率并管理货币政策。欧洲央行的主要任务是维持物价稳定,这意味着要么控制通胀,要么刺激增长。它的主要工具是提高或降低利率。相对较高的利率——或者更高利率的预期——通常对欧元有利,反之亦然。欧洲央行管理委员会每年召开八次会议,制定货币政策决定。决定是由欧元区国家银行行长和包括欧洲央行行长克里斯蒂娜·拉加德在内的六个常任理事国做出的。”
“欧元区通胀数据以消费者价格协调指数(HICP)衡量,是欧元的重要计量经济指标。如果通货膨胀率高于预期,特别是高于欧洲央行2%的目标,欧洲央行就不得不提高利率以控制通胀。与其他国家相比,相对较高的利率通常会对欧元有利,因为它使该地区作为全球投资者投资的地方更具吸引力。”
发布的数据可以衡量经济的健康状况,并可能对欧元产生影响。GDP、制造业和服务业pmi、就业和消费者信心调查等指标都可能影响欧元的走向。强劲的经济有利于欧元。这不仅会吸引更多的外国投资,还可能鼓励欧洲央行提高利率,这将直接增强欧元。否则,如果经济数据疲软,欧元可能会下跌。欧元区四大经济体(德国、法国、意大利和西班牙)的经济数据尤为重要,因为它们占欧元区经济的75%。”
“欧元的另一个重要数据是贸易平衡。该指标衡量的是一个国家在一定时期内出口收入与进口支出之间的差额。如果一个国家生产受欢迎的出口产品,那么它的货币将纯粹从寻求购买这些商品的外国买家创造的额外需求中获得价值。因此,净贸易余额为正会使货币走强,反之亦然。”
Related Articles