The information provided is of general nature only and does not take into account your personal objectives, financial situations or needs. Before acting on any information provided, you should consider whether the information is suitable for you and your personal circumstances and if necessary, seek appropriate professional advice. All opinions, conclusions, forecasts or recommendations are reasonably held at the time of compilation but are subject to change without notice. Past performance is not an indication of future performance. Go Markets Pty Ltd, ABN 85 081 864 039, AFSL 254963 is a CFD issuer, and trading carries significant risks and is not suitable for everyone. You do not own or have any interest in the rights to the underlying assets. You should consider the appropriateness by reviewing our TMD, FSG, PDS and other CFD legal documents to ensure you understand the risks before you invest in CFDs. These documents are available here.
Any references to Australian or international shares, sectors, indices, ETFs, crypto-related stocks or other instruments are provided for market commentary and watchlist purposes only and do not constitute a recommendation, offer or solicitation to buy, sell or hold any financial product or adopt any investment strategy. International markets may involve additional risks, including currency fluctuations, regulatory differences, market structure differences, reduced liquidity and higher volatility. Company-specific, sector-specific and macroeconomic risks may also affect performance.
Commentary on geopolitical developments, economic data, central bank decisions, earnings, policy changes and other global or financial market events is based on information available at the time of publication and may change without notice. Such events can lead to sudden market moves, price gaps, reduced liquidity, wider spreads and increased volatility, particularly in leveraged products such as CFDs. Forward-looking statements, expectations and scenario analysis are inherently uncertain and should not be relied on as guarantees of future market behaviour or outcomes.
日元因油价上涨增加进口成本而持续疲软
- 在以色列选举不确定性之际,高企的原油价格拖累日本这个能源进口型经济体,日元承压。
- 日本央行预计本周五将维持利率不变,市场已计入 12 月加息。
- 美联储预计今日将把目标利率维持在 3.75%-4.0% 不变,投资者正等待 12 月的信号。
周三亚洲时段,美元/日元连续第四个交易日上涨,交投于 158.00 附近。由于原油价格上涨给主要能源进口经济体带来新的成本压力,日元(JPY)面临挑战,美元/日元因此走强。
随着全球金融市场追踪以色列持续进行的选举结果,可能改变中东冲突的走向,油价上涨。出口民调显示,这场选举竞争激烈,结果显示总理本雅明-内塔尼亚胡与反对派领袖加迪-艾森科特打成平手,随着计票继续,双方都未能获得明确多数。尽管局势僵持不下,初步结果显示内塔尼亚胡的支持率正在下降;在过去近三年的冲突中,他一直领导国家,并在以色列政坛占据主导地位。
市场普遍预计,日本央行(BoJ)将在即将于周五举行的政策会议上维持利率不变。这是在年内早些时候累计加息 50 个基点之后,政策制定者暂停下来评估此前收紧政策的影响。然而,市场参与者仍预计年底前还会有一次加息,市场定价强烈倾向于 12 月加息。
同样,美联储(Fed)预计将在周三的决议中把基准利率维持在 3.75% 至 4.0% 的目标区间不变。根据 CME FedWatch 工具,市场对 10 月会议维持利率不变的概率定价为 92.8%。投资者将密切分析美联储主席凯文-沃什的讲话,以寻找有关未来政策路径的信号,尤其是在市场对 12 月加息的概率定价为 84.4% 的情况下。
技术分析:
日线图上,美元/日元交投于 158.00,维持建设性的看涨倾向,因为现货价格仍位于短期和中期指数移动均线(EMA)上方。50 期 EMA 位于 157.96,9 期 EMA 位于 157.76,均处在价格下方,表明逢低买盘兴趣仍在,而 14 天相对强弱指数(RSI)在 52 附近,使动能处于中性偏正区域,而非超买状态。
下行方面,近期支撑位于 157.96 附近的 50 期 EMA,而 157.76 的 9 期 EMA 则强化了回调时附近的需求区域。若进一步下跌,更远处的结构性支撑位于更广泛的 FXS Fed Sentiment Index 基础区域 127.51 附近,不过这与当前现货水平相距甚远,主要作为更长期的宏观参考。
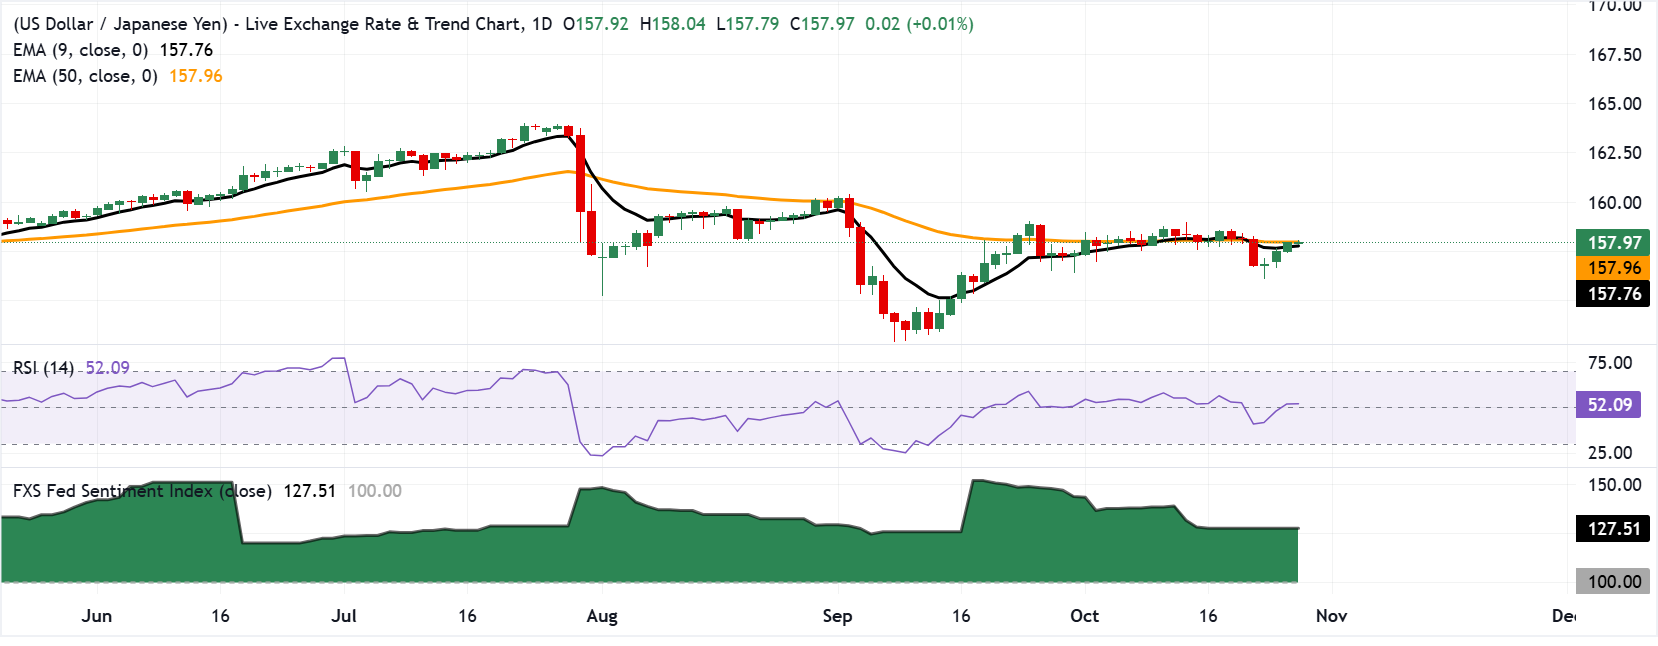
(本报道的技术分析由 AI 工具协助撰写。了解更多。)
日元常见问题(FAQ)
日元(JPY)是世界上交易量最大的货币之一。日元的价值大体上取决于日本经济的表现,但更具体地说,取决于日本央行(Bank of Japan)的政策、日美债券收益率之差,或交易员的风险情绪等因素。
“日本央行的任务之一是货币控制,因此它的举措对日元至关重要。日本央行有时会直接干预外汇市场,通常是为了降低日元的价值,不过由于主要贸易伙伴的政治担忧,日本央行通常不会这么做。由于日本央行和其他主要央行之间的政策分歧越来越大,日本央行在2013年至2024年期间的超宽松货币政策导致日元对主要货币贬值。最近,这种超宽松政策的逐渐退出给日元提供了一些支持。”
过去10年,日本央行坚持超宽松货币政策的立场,导致其与其它央行(尤其是与美联储(fed))的政策分歧不断扩大。这支撑了10年期美国国债和10年期日本国债之间利差的扩大,这有利于美元兑日元。日本央行在2024年决定逐步放弃超宽松政策,加上其他主要央行的降息,正在缩小这一差距。
日元通常被视为一种避险投资。这意味着,在市场紧张时期,投资者更有可能将资金投入日元,因为日元被认为具有可靠性和稳定性。动荡时期可能会使日元对其他被视为投资风险更大的货币升值。
Related Articles